The Demographic Certainty Defining the Future of Senior Housing
August 28, 2026
Updated: August 28, 2026
Every projection about the future of senior housing has pointed to this moment. Charts showing a steep demographic curve, analyses quantifying the 80+ population growth that was always “coming”, always something to prepare for. In 2026, the waiting ended. The first Baby Boomers turned 80 this year, and the growth phase that’s been anticipated for a decade has now officially begun.
No Longer a Forecast
The most unusual characteristic of demographic projection is its reliability. Unlike GDP forecasts or interest rate cycles, 80+ population growth over the next decade is not subject to revision.
What the data shows is acceleration. Census projections show the 80+ cohort expanding by one-third by 2030, two-thirds by 2035, and nearly doubling by 2040. This is an incremental 5 million people over 80 within five years, and 13 million within fifteen. That pace, once reached, holds for roughly two full decades.
Any senior housing market analysis built on these senior population trends starts from the same fixed inputs. They’re not speculative. They’re demographic arithmetic. And for a sector that has spent years making the case for structural demand, the shift from expectation to reality changes the conversation.
From “Arriving” to “Here”
When NIC MAP published its first Senior Housing Market Outlook in 2024, this was described as imminent. The first Boomers were projected to turn 80 in a milestone just ahead. The 2026 Senior Housing Market Outlook, Second Edition carries a different message: the future is now the present.
That change in tense matters more than it might first appear. For developers and lenders, it compresses the planning horizon. For operators, it validates occupancy gains that have extended for years without interruption. For investors, it removes the “not yet” objection from any thesis built on senior housing demand.
Demographic megatrends rarely announce themselves this profoundly. Most play out at the margins of data, with enough ambiguity to justify a wait-and-see stance. This one has a definitive start date and significant scale, and it’s starting now.
The Math Behind the Momentum
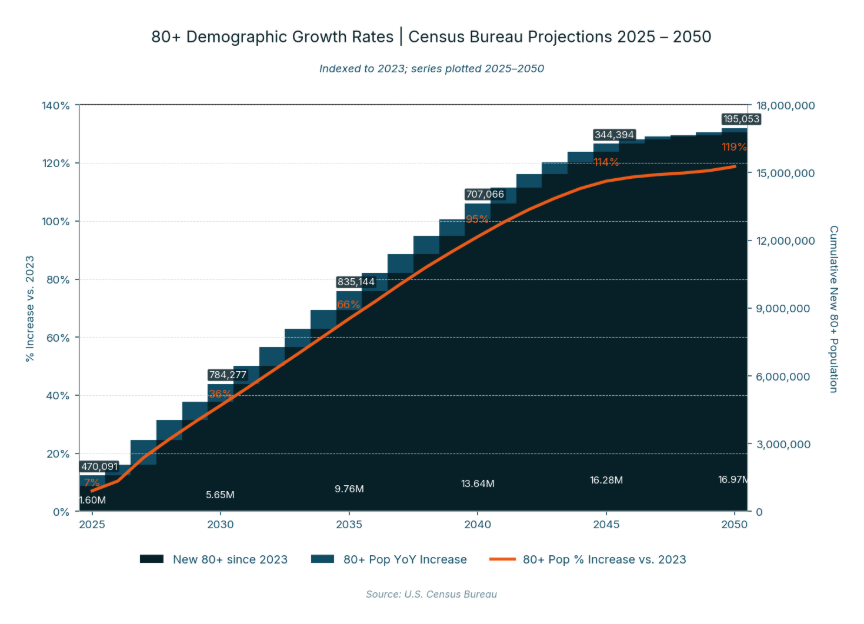
Industry-wide occupancy has risen more than 200 basis points in each of the last four years, driven largely by demand from cohorts already aging into the sector. What changes with the Baby Boomer wave is the rate of inflow. At 4 to 5 percent annual growth, the 80+ population will need to find housing at a pace the sector has never sustained at the scale required to meet this demand.
The senior housing benchmarks already reflect the setup. NIC MAP tracks occupancy across more than twenty years of data, and current levels are pressing near prior highs regarding demand and lows regarding construction.
Construction starts remain near generational lows, held back by the same economics that slowed development across real estate: elevated interest rates, construction costs that repriced after 2020, and persistent labor constraints. The senior care industry is attracting new investors in part because this gap, between accelerating demand and constrained new supply, is now visible in both public equity valuations and private transaction volumes.
The Question Is Scale, Not Direction
Senior housing occupancy, rent trends, and capital market activity have all moved in the same direction over the past two years. The sector has responded, and the data confirms it. What comes next is harder. Whether the financing structures, development pipelines, and operating platforms can scale fast enough to meet a cohort that arrives on a fixed schedule, that is the central question the future of senior housing now faces.
Frequently Asked Questions
When did Baby Boomers start turning 80?
The first Baby Boomers turned 80 in 2026, marking the start of the demographic growth phase the senior housing sector has anticipated for more than a decade.
How much will the 80+ population grow by 2040?
Census projections show the 80+ population expanding by roughly one-third by 2030, two-thirds by 2035, and nearly doubling by 2040.
Why is senior housing construction near historic lows?
Construction starts remain near generational lows, held back by elevated interest rates, construction costs that repriced after 2020, and persistent labor constraints.
Is now a good time to invest in senior housing?
Accelerating 80+ population growth on a fixed schedule is meeting constrained new supply, a gap now visible in both public equity valuations and private transaction volumes. The open question is whether financing, development, and operating platforms can scale to meet demand, not the direction of that demand.